Firstly, see how the FWD Invest First Max compares to other investment-linked policy plans in Singapore:

My review of FWD Invest First Max Review
I think the FWD Invest First Max is a long-term investment-focused ILP that suits people who are comfortable committing for many years and want bonus allocations to boost their policy value.
The main appeal is the bonus structure. You get a Booster Bonus of up to 93% in the first 2 years, a Loyalty Bonus from the 3rd policy year onwards, and an Accumulation Bonus at selected policy years if you keep paying premiums, avoid withdrawals, and do not reduce your premiums.
This can be attractive if you are disciplined and intend to stay invested for the full premium payment term.
The longer you stay committed, the more useful these bonuses become.
However, this is not a plan I would treat lightly.
Regular premium terms run from 10 to 30 years – making it a serious long-term commitment, not a short-term investment plan.
The charges are also important.
The Initial Account Charge is 6% p.a. in the first 10 policy years, then decreases to lower rates in subsequent years, while the Accumulation Account Charge starts from 1.6% p.a. and gradually reduces over time.
On top of that, recurring single premiums and top-ups have a 5% premium charge.
So while the bonuses look attractive, they need to be weighed against the policy charges and fund-level fees.
Poor fund performance, early withdrawals, premium reductions, or missed premiums can easily reduce the overall value of the plan.
I do like the flexibility.
You can make top-ups, recurring single premiums, withdrawals, fund switches, change the person insured, and change policy currency later on.
But most of these features come with timing rules and conditions, so they are not as freely available as they may sound.
Overall, I think FWD Invest First Max is more suitable for someone who wants a long-term ILP, can afford the premiums comfortably, and understands that returns are not guaranteed.
But if you want lower fees, stronger insurance coverage, or easier access to your money, this may not be the most suitable option.
Before deciding, compare this against other ILPs such as Manulife InvestReady III and Singlife SavvyInvest, or even non-ILP investment options if your main goal is wealth accumulation.
You should also compare the policy charges, fund choices, surrender terms, bonus conditions, and long-term projected returns before committing.
The main risks are the long commitment, early surrender charges, and the possibility of misunderstanding how the bonuses and fees work together.
A plan can look rewarding on paper, but still underperform if charges eat too much into returns.
Another option worth comparing is investing through iFAST with a financial advisor.
If your main goal is wealth accumulation, iFAST may give you access to a wider range of funds and more flexibility to top up, reduce, stop, or withdraw your investments.
We made a similar point in our FWD Invest First Plus review, where an iFAST setup with a 1% p.a. fee looked more attractive under that comparison.
That said, don’t assume iFAST is automatically better.
It depends on the advisor’s fees, fund selection, platform costs, and how your portfolio is managed.
But it is definitely something I’d compare against FWD Invest First Max before committing, especially since this ILP comes with long premium terms, surrender charges, and ongoing policy-level fees.
I strongly recommend getting a second opinion from a trusted financial advisor before buying this plan.
We’ve helped over 3,000+ Singaporeans review their insurance and investment plans, and many only realised the impact of fees and lock-ins after getting a proper comparison.
Speak with one of our financial advisors to get a free non-obligatory consultation before making your final decision.
Click here to get a free non-obligatory consultation.
Criteria
- Minimum investment period of 10 to 30 years
- Invest from $300/month
- Currency options: SGD, USD, GBP, and AUD
General Features
Minimum Regular Premiums
Premiums are payable throughout your selected premium payment term, which can range from 10 to 30 years.
For premium payment terms of 10 to 19 years, the minimum regular premiums are:

For premium payment terms of 20 to 30 years, the minimum regular premiums are lower:

Regular premiums paid during the first 24 months from the effective date are used to buy units allocated to the initial units account.
After that, future regular premiums are allocated to the accumulation units account.
Death Benefit
The FWD Invest First Max pays a Death Benefit of 105% of the Policy Value when the person insured passes away.
If there is more than 1 person insured under the policy, the Death Benefit will only be paid when the last person insured passes away.
Key Features
Booster Bonus
FWD Invest First Max pays a Booster Bonus during the first 2 policy years whenever your regular premium is received.
The bonus is calculated as:
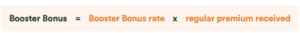
Your Booster Bonus rate depends on your annualised regular premium and selected premium payment term.


In simple terms, the higher your annualised premium and the longer your premium payment term, the higher your Booster Bonus can be.
These units are credited into the initial units account of the base layer or increase regular premium layer.
However, the bonus is conditional. If you miss any regular premium payment during the first 2 policy years of the base layer or any increase regular premium layer, the Booster Bonus will not be paid.
The Booster Bonus also does not apply to top-up premiums or recurring single premiums.
Loyalty Bonus
The FWD Invest First Max rewards long-term policyholders with a Loyalty Bonus that starts from the end of the 3rd policy year and continues throughout the policy term.
During the premium payment term, the Loyalty Bonus is calculated using the following formula:
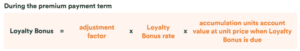
The Adjustment Factor is calculated as:

The Adjustment Factor cannot be less than 0 or greater than 1.
After the premium payment term ends, the calculation becomes simpler:

This means the Adjustment Factor no longer applies after the premium payment term, and the policy continues paying a Loyalty Bonus every year as long as the policy remains in force.

If you increase your regular premium and create an increased regular premium layer, the Loyalty Bonus is calculated separately for each layer based on:
- The Loyalty Bonus rules applicable to that layer, and
- The policy year of that specific increase regular premium layer.
Accumulation Bonus
The FWD Invest First Max also pays an Accumulation Bonus at certain policy years while the policy is in force.
This bonus is only paid if all 3 conditions are met:
- No withdrawal was made in the prior 60 months
- No reduction in regular premium was made in the prior 60 months
- All regular premiums due were paid in the prior 60 months
If these conditions are met, the Accumulation Bonus is calculated based on your accumulation units account value and any top-up premium paid in the current policy year.
The formula is:

The pro-rated Accumulation Bonus rate is calculated based on how long the top-up premium has been in the policy during that policy year:

The applicable Accumulation Bonus rate on a per annum basis is set out below:

Top-up premium
The FWD Invest First Max allows you to make top-up premiums at any time, giving you the flexibility to invest additional funds without increasing your regular premium commitment.
The minimum top-up amount is:
- S$3,000
- US$2,250
- £1,840
- AU$3,260
Change of person insured
The FWD Invest First Max allows you to change the person insured while the policy remains in force.
You may request this change from the 25th month onwards after the base layer takes effect.
The new person insured must:
- Be at least 1 month old
- Be below 65 years old
Change of policy currency
This option is available from the 25th month onwards after the base layer takes effect, provided the policy remains in force.
However, any currency conversion will be subject to the applicable exchange rates at the time of the conversion.
Increase in regular premium
You may increase your regular premium beyond the annualised amount committed to the base layer if both conditions are met:
- The request starts from the 13th month of the base layer onwards
- There are 10 or more years remaining before the premium payment term ends
Once approved, each increase will create a separate increase regular premium layer.
You may request to increase your regular premium up to 2 times a year, but approval depends on whether FWD makes this option available and accepts the request.
For each increase regular premium layer, you must select a preferred premium payment term.
If the request is made before the policy anniversary and your premium frequency is not annual, the actual premium payment term duration for that layer may differ from your selected term.
The first 24 months of each increase regular premium payment will be allocated to the initial units account.
After that, premiums will be allocated to the accumulation units account.
Each increase regular premium layer is entitled to its own Booster Bonus, Loyalty Bonus, and Accumulation Bonus.
It will also be subject to its own Initial Account Charge and Accumulation Account Charge, based on the terms of that layer.
The minimum increase in regular premium can be found in the relevant forms and may change from time to time.

If you previously reduced your regular premium, FWD will first increase your premium back up to the total annualised amount originally committed for the base layer and any increase regular premium layer before considering any further increase.
If you changed your policy currency after reducing your regular premiums, FWD will inform you of the maximum premium increase allowed in the new policy currency.
Reduction in regular premium
You may apply to reduce your regular premium from the 25th month onwards after the base layer takes effect.
This is subject to:
- The minimum regular premium
- The minimum reduction requirements of $50 in the policy currency
These requirements can be found in the relevant application form and may change from time to time.
If you are also paying recurring single premiums or have any increase regular premium layers, FWD will reduce those first before applying any reduction to the regular premium in your base layer.
Withdrawal options
The minimum withdrawal amount is S$500, US$375, £300, or AU$540, whichever applies.

During the first 24 months of each policy layer, withdrawals are not allowed from either the initial units account or the accumulation units account.
From the 25th month onwards, withdrawals may be made from the accumulation units account during the premium payment term.
After the premium payment term ends, withdrawals can be made from the Policy Value, subject to the minimum account value requirements.
If you previously increased your regular premium, withdrawals will be taken from the most recent increase regular premium layer first, followed by the next latest layer, and lastly from the base layer.
During the premium payment term, the minimum accumulation units account value after withdrawal must be:

After the premium payment term, the minimum Policy Value after withdrawal must be:

FWD may change the minimum account value at any time.

FWD Invest First Max Top 10 Performing Funds
Here are the FWD Invest First Max top 10 performing funds:
| Fund Name | Currency | 5-Yr Ann. (%) |
| Lazard Emerging Markets Equity Fund USD Acc | USD | 14.27 |
| Allianz Best Styles Global Equity Fund SGDH Acc | SGD | 13.12 |
| Check-box for table item
Amova Singapore Dividend Equity Fund SGD Dis |
SGD | 12.45 |
| Infinity US 500 Stock Index Fund USD Acc | USD | 12.30 |
| GS Europe CORE Equity Fund EUR Acc | EUR | 11.82 |
| Allspring Global Equity Enhanced Income Fund SGDH Dis | SGD | 11.07 |
| Infinity US 500 Stock Index Fund SGD Acc | SGD | 10.74 |
| Check-box for table item
Guinness Global Innovators Fund USD Acc |
USD | 8.87 |
| Natixis Loomis Sayles US Growth Equity Fund SGD Acc | SGD | 8.37 |
| Neuberger US Multi Cap Opportunities Fund USD Acc | USD | 8.28 |
Accurate as of August 2026.
As always, past performance should not be relied upon as an indication of future results.
FWD Invest First Max Fees & Charges
Initial account charge
The Initial Account Charge is one of the main ongoing charges under the FWD Invest First Max.
It applies throughout the selected premium payment term and is deducted every month on each policy monthiversary.
The charge is calculated using the following formula:

The applicable A% depends on your selected premium payment term and policy year.

Each increase regular premium layer is also subject to its own Initial Account Charge.
The charge is calculated in your policy currency and allocated across the ILP sub-funds in your initial units account based on their net asset value.
Accumulation account charge
The Accumulation Account Charge is an ongoing policy charge that applies throughout the entire policy term and is deducted every month on each policy monthiversary.
The charge is calculated using the following formula:

Each increase regular premium layer is also subject to its own Accumulation Account Charge.
The applicable charge rate depends on the policy year of that specific layer.

Premium charge (recurring single premium and topup premium)
The FWD Invest First Max applies a 5% Premium Charge on every recurring single premium and top-up premium.
This charge is deducted before your money is invested into the selected ILP sub-funds.
For example:
- A S$10,000 top-up premium will incur a S$500 premium charge.
- The remaining S$9,500 will be used to purchase units in your chosen ILP sub-funds.
The same 5% charge applies to recurring single premiums.
Policy closure charge
The FWD Invest First Max applies a Policy Closure Charge when the policy no longer has enough value to remain in force.
If the Policy Value falls below S$1, or the equivalent amount in the policy currency, FWD will treat the policy as having insufficient value and will apply this charge to close the policy.
The Policy Closure Charge is fixed at: S$1 (or the equivalent amount in the policy currency)
Once the charge is applied, the policy will end.
Surrender charge
A Surrender Charge applies if the FWD Invest First Max is surrendered before the end of the selected premium payment term.
The surrender charges are shown below:

Change in policy currency charge
There is no charge for changing your policy currency.
While there is no charge for the currency change itself, any impact arising from foreign exchange movements will depend on the exchange rates applicable at the time of the conversion.
Redemption fee (also known as partial withdrawal or regular withdrawal charge)
FWD does not apply any redemption fee on partial withdrawals or regular withdrawals.
This means you will not be charged when withdrawing money from the policy, subject to the withdrawal rules and minimum account value requirements stated in the policy.
While there is no withdrawal charge, withdrawals will reduce your Policy Value and may affect future bonuses and investment growth.
Switching fee
FWD currently keeps the Switching Fee at zero.
However, this charge may be reviewed in the future with at least 30 calendar days’ written notice given to you.
Fund management charge
The Fund Management Charge is not deducted separately from your policy.
Instead, it is already taken into account when the unit price of the ILP sub-fund is calculated.
The applicable Fund Management Charge depends on the specific ILP sub-fund selected.
To understand the exact charge for a particular fund, you will need to refer to the relevant fund documents provided by FWD.
References
https://www.comparefirst.sg/wap/prodSummaryPdf/200501737H/WA_Sum_200501737H_ILP05_RP_Feb2024.pdf